
While the S&P 500 is up 16.3% since April 2026, Tetra Tech (currently trading at $33.72 per share) has lagged behind, posting a return of 8.5%. This might have investors contemplating their next move.
Is TTEK a buy right now? Or is its underperformance reflective of its business quality?
Why Does Tetra Tech Spark Debate?
With a 50-year legacy of "Leading with Science" and operations on all seven continents, Tetra Tech (NASDAQ:TTEK) provides high-end consulting and engineering services focused on water management, environmental solutions, and sustainable infrastructure for government and commercial clients worldwide.
Two Things to Like:
1. Skyrocketing Revenue Shows Strong Momentum
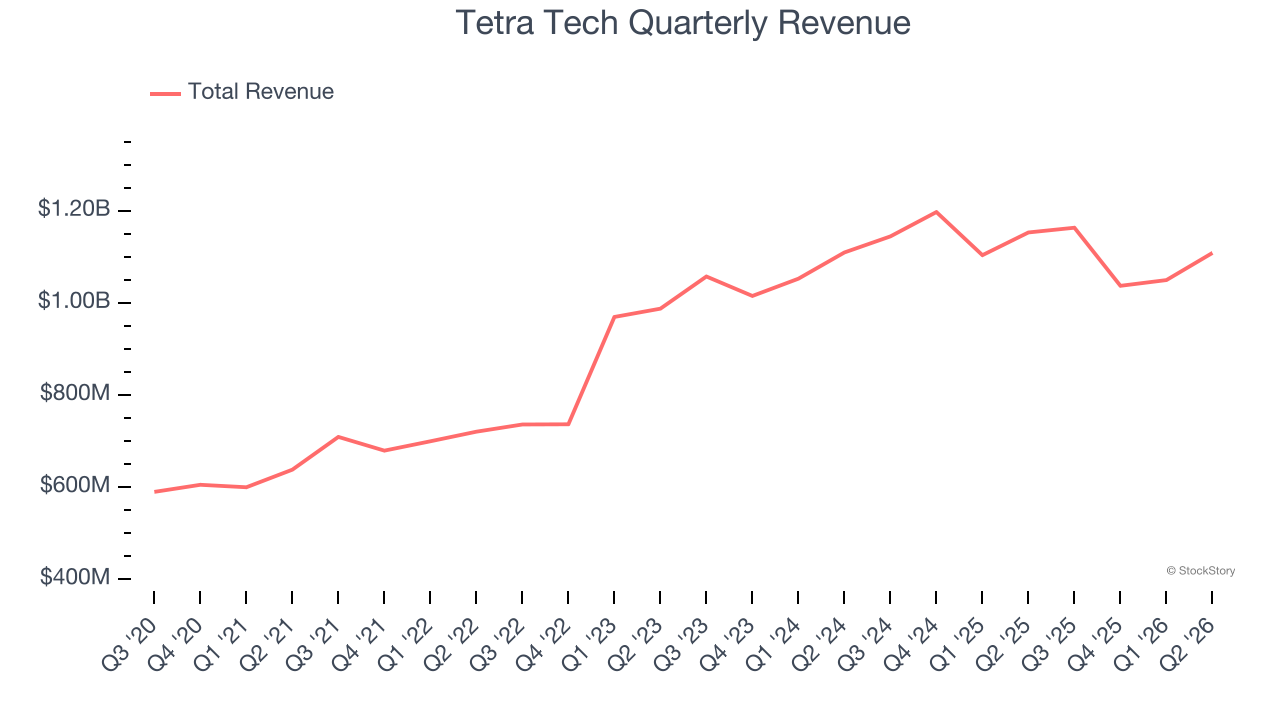
A company’s long-term sales performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Over the last five years, Tetra Tech grew its sales at an excellent 12.4% compounded annual growth rate. Its growth surpassed the average business services company and shows its offerings resonate with customers.
2. Outstanding Long-Term EPS Growth
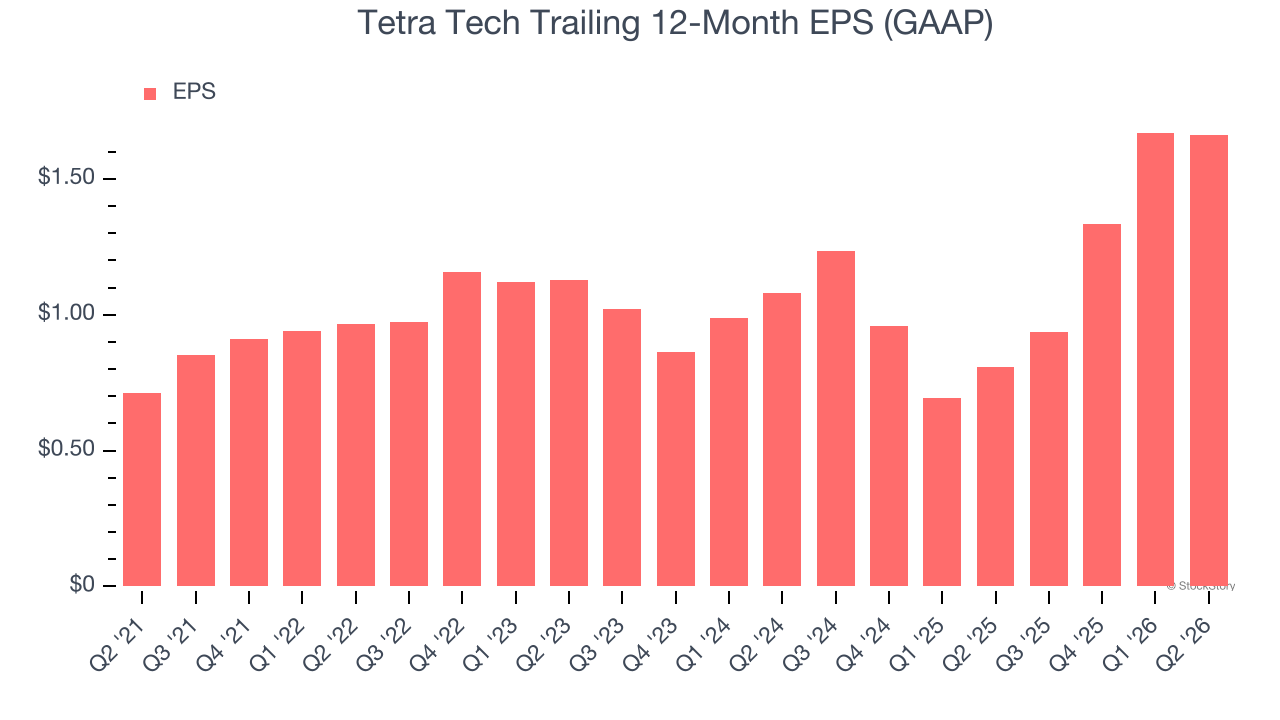
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Tetra Tech’s EPS grew at 18.5% compounded annual growth rate over the last five years, higher than its 12.4% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
One Reason to Be Careful:
Projected Revenue Growth Is Slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Tetra Tech’s revenue to rise by 3.4%. While this projection implies its newer products and services will spur better top-line performance, it is still below average for the sector. At least the company is tracking well in other measures of financial health.
Final Judgment
Tetra Tech’s merits more than compensate for its flaws. With its shares trailing the market in recent months, the stock trades at 19.5× forward P/E (or $33.72 per share). Is now a good time to initiate a position? See for yourself in our comprehensive research report, it’s free.
Stocks We Like Even More Than Tetra Tech
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.